Breeder life & families · the work behind the litter
Build a litter budget that includes overlooked work
Count the work you can’t find on a receipt.
The budget has a laundry problem.
A litter budget needs room for the small repeat purchases, the hours between them and the things you still can’t price. Start with your records, then leave the unknowns visible.
Make a budget review sheet ↓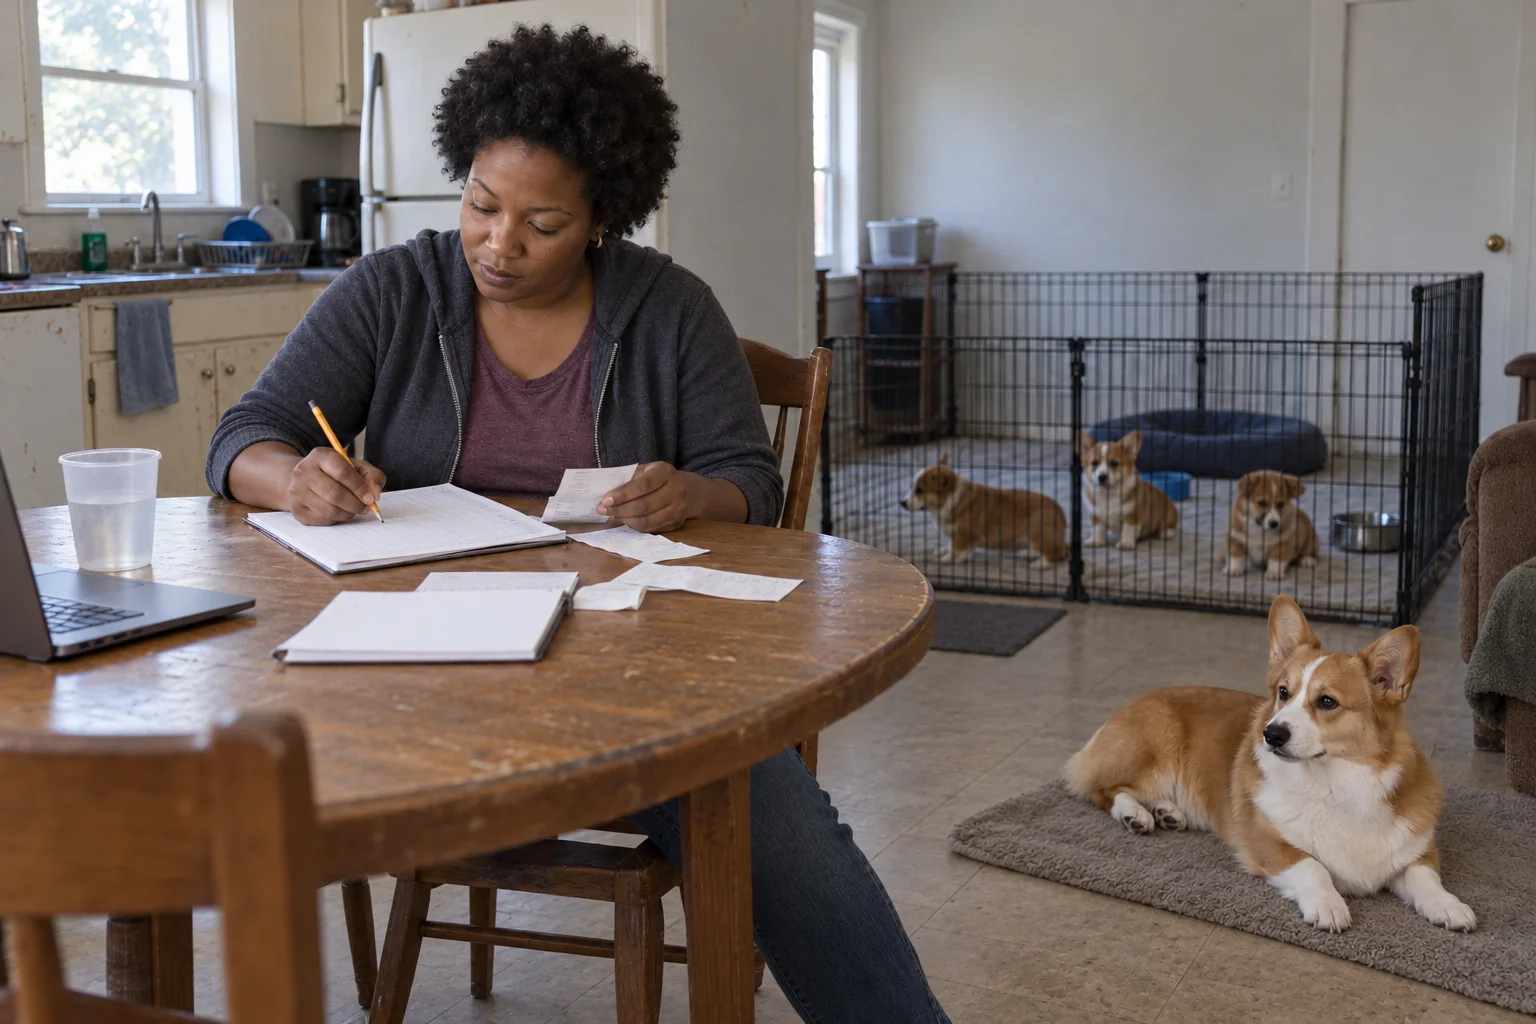
Start with the day, then open the receipts.
The obvious purchases will usually make it into a budget. The extra load of washing, the drive to collect supplies and the evening spent answering families are more likely to disappear. A receipt can tell you what you bought. It can’t tell you how long you spent making the purchase useful.
Walk through the work before you total the money: preparation, daily care, go-home arrangements and support afterward. For each part, ask what gets paid for, what gets used up, who does the job and what might change. You’re building a picture you can revisit, rather than trying to produce one impressive number.
The AKC’s breeding guide names feeding, cleanup, grooming, training and veterinary care as substantial work. That gives you a reason to look beyond the initial shopping list; it doesn’t give you a standard number of hours or a standard bill. Breeder guidance ↗
Reference sheet 01 · five things worth separating
Money paid. Time spent.
Questions still open.
Keep these distinctions beside your ledger. They stop a useful estimate from becoming a misleading total.
| What to record | Keep this distinction |
|---|---|
| Reusable equipment | A purchase can serve more than one litter. Record the cash paid when you buy it. If you also allocate a share to a litter, label that share so the purchase is not counted twice. |
| Supplies you use up | Small repeat purchases deserve a line. Food, laundry products, disposable supplies and printing can be easy to miss when you remember only the large bills. |
| Paid help | Cash and coverage are separate details. Record the amount paid, what the person covered and the dates. Keep their hours separate from your own. |
| Your time and unpaid help | Hours belong in the picture even without an invoice. Track the task and time. If you later attach a value, label the rate and calculation separately from cash spending. |
| Uncertain costs | An unknown amount is not zero. Write what needs an estimate, who will provide it and when you will check again. Keep contingency separate from money already spent. |
Original Good Harbor bookkeeping prompts. These categories describe the work; they do not set prices, accounting rules or a recommended reserve.
Let the little jobs stay little—and visible.
You don’t need to time every movement with a stopwatch. Choose a record you can keep: a short task log, notes at the end of a care period, or the record system you already use. State the dates it covers. A quiet day and a difficult day may tell different stories.
Include work that happens away from the dogs: booking appointments, obtaining reports, talking with families, arranging cover, preparing materials and following up. If two jobs overlap, note that rather than quietly counting the same stretch of your time twice.
Unpaid help is still help you rely on. Record what that person actually does and whether they can do it again. A relative covering one afternoon is a different arrangement from a dependable paid caregiver. The difference matters when you plan the next litter.
Give every uncertain amount a next step.
Ask your own suppliers, veterinary practice and caregivers for relevant estimates. Keep the date and what is included beside each one. An estimate for a routine service is not an estimate for every possible complication. If you don’t know, write “to confirm” and the person you will ask.
SBA’s general business guidance separates one-time and recurring expenses and recommends checking costs with suppliers and service providers. For this work, the useful habit is traceability: you should be able to tell where an amount came from and what it covers. Cost-planning guidance ↗
Keep possible future puppy income separate from costs already incurred and care that still has to happen. A hopeful income line doesn’t arrange cover, buy supplies or settle an outstanding bill. You can record possibilities without treating them as settled facts.
Reference sheet 02 · make it useful
The work behind this litter
Take this through your actual records. Keep amounts, hours and unresolved estimates clearly labeled; this sheet does not calculate a price or profit.
The work behind this litter
Date / version: ____________________
Planning notes, not a tax ledger. Keep receipts and original records separately. Use your own local estimates.
Notes stay on this page until you leave or reload. Download a copy to keep them. This page does not save notes to an account.
Use the next review to improve one thing.
After the litter, compare estimates with the actual records and revisit the time log. Which job took more attention than expected? Which recurring purchase kept slipping off the list? Which piece of equipment did useful work across several litters?
Choose one practical change: get a clearer quote, arrange cover earlier, keep supplies easier to count, or allow more time for family handovers. The budget earns its place when it helps you make those decisions. The laundry, regrettably, will still need doing.
Read further
What supports this framework.
Breeder guidance identifies the commitment; general business guidance helps separate cost types. Neither supplies an average cost for your litter.
- American Kennel Club
Guide to Responsible Dog Breeding ↗
US breeder education. The commitment section describes expenses and work; the lifelong-support section describes continuing contact. Undated current web guidance, checked October 10, 2026.
- US Small Business Administration
Plan your business · calculate startup costs ↗
General business guidance on identifying costs, obtaining estimates and separating one-time and recurring expenses. This is not a survey of breeding costs.
How the evidence is used
AKC’s commitment section supports the workload and cost categories, without industry cost or hourly averages. The article’s ledger distinctions and review prompts are original editorial reasoning.
SBA’s startup-cost guidance separates one-time and recurring expenses and directs readers to estimates. It is applied as a classification idea, not breeder-specific financial evidence. No cost, wage, litter size, expected income, profit or tax treatment has been invented.
Finished reading?
Keep track of the guides you’ve explored.
Sources checked October 10, 2026. Accounting and tax treatment depend on your own circumstances.